Ripple National Trust Bank Final Approval: What It Means for XRP
The OCC gave Ripple final approval for a national trust bank on October 26, 2026. What the bank can do, what it can't, and why its approved activities skip XRP.
Key takeaways
- On October 26, 2026 Ripple announced final OCC approval for Ripple National Trust Bank, nearly six years after the SEC sued it on December 22, 2020.
- Ripple's release says the bank's approved activities include managing RLUSD's segregated reserves, acting as collateral trustee of those reserves for RLUSD holders, and digital asset custody.
- A national trust bank takes no deposits and makes no loans. It works as a supervised vault, not a lender.
- The approved-activities sentence in Ripple's release does not name XRP. Separately, a March 17, 2026 SEC and CFTC interpretation named XRP among 18 digital commodities.
- Before believing any 'Ripple is a bank' headline, check whether the letter says conditional or final, and whether the bank has actually opened.
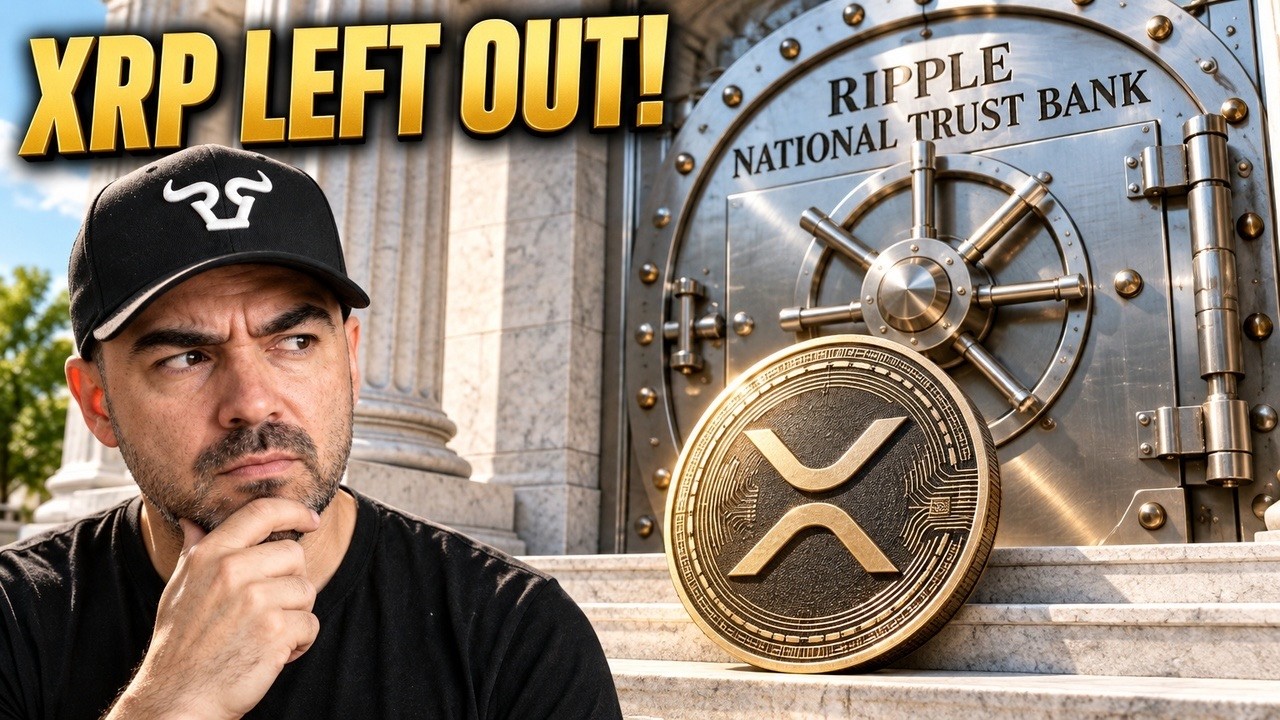
Ripple announced on October 26, 2026 that the Office of the Comptroller of the Currency (OCC) had granted final approval for Ripple National Trust Bank. The bank’s approved activities include managing the reserves behind Ripple’s RLUSD stablecoin and providing custody services. It cannot take deposits or make loans, and its list of approved activities does not mention XRP.
That gap matters for anyone who has held XRP on the idea that the day banks let Ripple in is the day the coin finally benefits. A Bullrunners video walks through the nearly six years between the SEC lawsuit and the bank charter, then reads the approval line by line. Its conclusion is that Ripple the company got something real, but the letter gives XRP nothing directly.
How did Ripple go from SEC lawsuit to federal bank?
Ripple went from being sued by the SEC in December 2020 to receiving a federal trust bank charter in October 2026. The path ran through a court ruling, dropped appeals and a two-step OCC approval. The video lays out the timeline:
- December 22, 2020: The SEC sued Ripple. Page one of the complaint says Ripple sold 14.6 billion XRP, worth $1.38 billion, as a security it never registered.
- Late December 2020: Exchanges began pulling back. Bitstamp announced it would stop XRP trading for US customers. OKCoin announced on December 28 that it would suspend XRP trading from January 4, 2021. Coinbase announced a suspension that took effect on January 19, 2021. Per the video, XRP traded around 19.9 cents on December 29, 2020, about 12 hours after Coinbase’s announcement. The video says that was down 31% in a day, from above 60 cents a month earlier.
- July 13, 2023: Judge Analisa Torres ruled that XRP sold to regular buyers on exchanges was not a security. Per the video, XRP rose from about 47 cents to about 82 cents that afternoon. The same ruling found that Ripple’s direct sales to large investors did break the law.
- July 2, 2025: While the case was still open, Brad Garlinghouse announced that Ripple was applying to the OCC for a national bank charter.
- August 7, 2025: Both sides dropped their appeals. The $125,035,150 penalty from the final judgment stayed. The video says the SEC’s release confirms the judgment remains in effect.
- December 12, 2025: The OCC granted conditional approval.
- October 26, 2026: Garlinghouse posted that the OCC had granted final approval, the day before Ripple’s Swell conference.
The video argues that Ripple never wanted out of the system. On the day of the lawsuit, Garlinghouse complained that the SEC was “picking winners” by treating Bitcoin and Ether differently from XRP. In the video’s reading, his complaint was about being left outside the rules, not about rules existing.
Why did Ripple want a second regulator?
Ripple wanted OCC oversight on top of its New York trust license so that its stablecoin business would be, in Garlinghouse’s words, “almost overregulated” on purpose. Ripple’s subsidiary Standard Custody is a New York trust company regulated by the New York Department of Financial Services. Ripple acquired it, and it now issues RLUSD.
In a clip the video dates to February 2026, Garlinghouse described the OCC charter as “belt and suspenders regulatory oversight for our stablecoin business.” As the video puts it, the plan was to be regulated twice, once by New York and once by Washington. The GENIUS Act became law in July 2025 and set federal rules for dollar stablecoins. Ripple’s application was already in by then.
For a closer look at the earlier stage, see Bullrunners’ explainer on what the OCC charter letter actually says.
What is the difference between conditional and final approval?
Conditional approval is permission to go build the bank. Final approval comes only after the OCC is satisfied that pre-opening requirements are met. When the December 2025 news broke, many headlines ran with “Ripple is now a bank.” That was premature.
The video quotes an OCC charter letter dated September 18, 2026, written for a different applicant with the same type of charter. According to the video, the letter says final approval for the bank to commence business will not be granted until pre-opening requirements are met. The video describes that as money set aside, people hired, controls built and an OCC inspection.
The video offers a one-word test for any “Ripple is a bank” headline: does the letter say conditional or final? Even now that it says final, the video notes the bank still needs an opening date before it is actually operating.
What is Ripple National Trust Bank allowed to do?
Ripple’s own release says the bank’s approved activities include three things:
- managing the segregated reserves supporting RLUSD
- acting as collateral trustee of the reserves for the benefit of RLUSD holders
- providing fiduciary digital asset custody services
The release says the activities “include” these, so the list may not be complete.
In plain words, the video translates these as:
- Reserve management: Hold the cash and Treasury bills behind RLUSD in a separate pile.
- Collateral trustee: Act as trustee of that pile, so it belongs to RLUSD holders, not to Ripple, if Ripple ever fails.
- Custody: Hold crypto for business clients under the rules that govern a bank trust department.
What the bank cannot do matters just as much. Reporting on the approval says it takes no deposits and makes no loans. The video adds that OCC charter letters say a trust bank limits its operations to those of a trust company. The video calls it “a vault with a federal inspector.”
Trust banks are not small, though. Per the video, the OCC’s letter says the trust banks it supervises held $7.2 trillion for other people as of March 31, 2026.
| Activity | Status for Ripple National Trust Bank |
|---|---|
| Manage RLUSD’s segregated reserves | Named in Ripple’s release |
| Act as collateral trustee for RLUSD holders | Named in Ripple’s release |
| Digital asset custody for clients | Named in Ripple’s release |
| Take customer deposits | Not allowed |
| Make loans | Not allowed |
Does the bank charter help XRP?
The approved-activities sentence in Ripple’s release does not name XRP. It names RLUSD twice and custody once. The video also counts Garlinghouse’s announcement post and finds RLUSD named once, custody once and XRP zero times.
The video stresses this is not a trick. It reflects what the bank is for. The video says about $2.58 billion of RLUSD was in circulation on October 26, 2026, and the bank’s first job is guarding the reserves behind it. The video puts XRP’s circulating supply that day at about 63.35 billion, a figure that varies by data source. The letter says nothing about any of them.
What about custody? The video’s answer is “maybe.” The custody business serves companies, not retail holders. Whether a large customer asks the vault to hold XRP, Bitcoin or a tokenized fund is that customer’s decision. Nothing in the letter puts XRP in the vault. This fits a pattern Bullrunners has covered before on why a Ripple win isn’t automatically an XRP win.
What actually changed XRP’s legal status?
XRP’s status was addressed in a separate document. On March 17, 2026 the SEC, joined by the CFTC, published an interpretation listing 18 crypto assets, including XRP, as digital commodities. According to the video, that paper moved XRP from security to commodity, and the bank charter did not. The interpretation also notes that a digital commodity can still be part of an investment contract, which would bring securities laws back into play.
The video frames the two documents as answering two halves of the 2020 question. For the company, the video says the government went from calling Ripple an illegal securities seller to treating it as fit to guard other people’s money under federal inspection. For the coin, the commodity interpretation did the work. The host adds that the charter contains nothing that lifts XRP directly, which is why he is also watching the next steps for the CLARITY Act.
The video raises one longer-term point about custody. If your coins sit on an exchange, the video says that exchange’s filings describe you as a creditor if it fails. A federally supervised trust bank holding coins as a trustee is a different legal arrangement. That is a question of who holds your coins, not of price. It connects to Bullrunners’ guide on who really owns your XRP.
Ripple was also not alone. On December 12, 2025, the OCC conditionally approved five firms on the same day: Ripple, Circle, Paxos, BitGo and Fidelity Digital Assets. On October 21, 2026, five days before Ripple’s final approval was announced, Comptroller Jonathan Gould’s OCC issued its final rule implementing the GENIUS Act for stablecoins. In Ripple’s December release, Garlinghouse called opponents of the charters “anti-innovation bank lobbyists.”
A simple check for any Ripple bank headline
This Bullrunners checklist builds on the video’s conditional-or-final test and its advice to read the document itself:
- Find the actual letter or release, not the thumbnail.
- Check the key word: conditional or final.
- Check whether the bank has announced an opening date.
- Read the approved-activities sentence and note which assets are named.
- Ask whether the news is about Ripple the company or XRP the coin.
What to watch next
Swell, Ripple’s conference, runs October 27 to 29, 2026 in New York. Garlinghouse has pitched Ripple as a bridge between traditional finance and decentralized finance. The video suggests listening for two things. The first is an opening date for Ripple National Trust Bank, since final approval does not mean open for business. The second is whether any customer, rather than Ripple, says it wants the custody business to hold XRP.
The video’s closing summary is that Ripple got into the building, while XRP still trades in the same marketplace it did before. It says nothing in this letter changes that.
Sources
- SEC complaint against Ripple (December 22, 2020)
- SEC litigation release, appeals dismissed (August 2025)
- Ripple, OCC conditional approval (December 12, 2025)
- SEC and CFTC interpretation listing XRP as a digital commodity (March 17, 2026)
- OCC Corporate Decision 1393 (September 18, 2026)
- Ripple, final OCC approval for Ripple National Trust Bank (October 26, 2026)
- Crypto Briefing, no deposits and no loans (October 26, 2026)
Frequently asked questions
Is Ripple a bank now?
Ripple announced final OCC approval for Ripple National Trust Bank on October 26, 2026, following conditional approval on December 12, 2025. According to the video, final approval is still not the same as being open for business, so an opening date is the next thing to watch.
Can Ripple National Trust Bank take deposits or make loans?
No. Reporting on the approval says the bank takes no deposits and makes no loans. The video adds that OCC charter letters say a trust bank limits its operations to those of a trust company.
Does Ripple's bank approval mention XRP?
Not in the list of approved activities. That sentence in Ripple's release names RLUSD twice, custody once and XRP zero times. The video says Garlinghouse's announcement post also did not name XRP.
Is XRP a security or a commodity?
On March 17, 2026 the SEC, joined by the CFTC, published an interpretation listing 18 crypto assets, including XRP, as digital commodities. The interpretation also notes that a digital commodity can still be part of an investment contract, which would bring securities laws back into play.
How did the SEC lawsuit against Ripple end?
Judge Analisa Torres ruled on July 13, 2023 that XRP sold to the public on exchanges was not a security, but that Ripple's direct sales to institutions broke the law. Both sides dropped their appeals on August 7, 2025, and the $125,035,150 penalty stayed in place.
Full video transcript
From the video's captions, lightly formatted. Captions can mishear names and numbers, so check figures against the article above.
that investors may have thought that in buying XRP they were buying a security that gave them shares or some ownership in Ripple. Why is that wrong on its face?
Well, first of all, Tyler, thanks for having me. I think this is an important issue and I think there has been confusion out there. Ripple as a company, as Kate introduced, we have shareholders. We've raised capital from venture capitalists, from actually institutions and even banks like Standard Charter is a shareholder. XRP is a separate thing altogether.
It is a currency that trades in the marketplace.
That's Brad Garlinghouse on CNBC on the afternoon of December 22nd, 2020. That morning, the United States government sued his company. Page one of the lawsuit says Ripple sold 14.6 6 billion XRP worth $1.38 billion as a security it never registered. If you were holding XRP that night, you were holding a coin the government had just called illegal to sell. Nearly 6 years later, on October 26th, 2026, that same government's bank regulator signed a letter making Ripple a federal bank.
Same company, same coin on the same ledger. And the letter does something almost nobody who bought XRP on the Ripple is a bank now headline has read. If you hold XRP because you were told the day the banks let Ripple in is the day your coin finally gets paid, that day has a date now. It was October 26, 2026. So the question this whole video answers is simple.
What did Ripple get in that letter? And what did your coin get? Because those are two different answers. And the second one is the one that costs you money if you guess. So if you're feeling bullish, like this video and smash that subscribe button.
We're on our way to 400,000 subscribers. And if you're going to be the first millionaire in your family tree, confirm that by commenting amen down below. Also, we are giving away our 2026 altcoin trading strategies and crypto yield generation briefing to everyone who follows us on Instagram @bullrunners. The official link is in the description down below this video. Let's run it.
All right, bull runners. Ryan Huggin here, aka WinW with Ryan. Welcome back to the channel. So, go back to that week in December of 2020.
Breaking news. Coinbase just announced they will be delisting XRP from their platform and they will suspend all trading starting next month. 6 days after the suit, Coinbase said it would stop trading XRP. Bitstamp had already stopped. OKCoin stopped that same day.
This comes after the huge fall from 60 cents, 60 plus cents down to 25 cents. So basically all the gains from the last few weeks going up all the way up to about uh 80 cents and then falling to about 60 cents, you know, hovering there and then basically all that has been wiped out all due to this lawsuit from the SEC. On December 29th, 2020, 12 hours after Coinbase's announcement, XRP traded at 19.9, down 31% in 1 day. A month earlier, it had been over 60. Think about what that is in a real account. $10,000 of XRP on Thanksgiving was about $3,300.
By New Year's Eve, the biggest store in America had taken it off the shelf. The very first thing I started doing was scrambling for other exchanges that were international that you could either buy or sell XRP at because there had to be something available to us. But here's what the headlines missed that week. Ripple didn't want out of the system. Ripple wanted in.
But listen to what Garlinghouse was angry about on day one.
The SEC is really picking winners. They're saying there's a duopoly of Bitcoin and Ether are the two digital assets, the cryptocurrencies that will be not regulated by the SEC here in the United States. And it really, I think, sends an ominous sign for innovation around cryptocurrency in the United States. Picking winners in general has not been something the US government should be in the business of doing.
Picking winners. His complaint wasn't that the government had rules. It was that the government had put Bitcoin and Ether inside the rules and left XRP outside. So, Ripple spent the next 2 and 1/2 years in court trying to get inside.
Also happening this morning, a district court judge in New York just delivered a huge win for Ripple and its case against the SEC. In the ruling, the judge said the XRP token is quote, "not necessarily a security on its face. That decision was seen as a key hurdle for the crypto industry amid huge scrutiny in 2023."
On July 13th of 2023, Judge Anna Lisa Torres ruled that XRP sold to regular people on exchanges was not a security. XRP went from about 47 cents to about 82 cents that afternoon. This was kind of a landmark ruling and and one that uh let uh crypto enthusiasts and advocates really puff out their chest, I think, for the first time in in several months and and perhaps years. Um all this stems back to a a landmark suit that the SEC issued against a company called Ripple Labs based in San Francisco.
That's the day most people remember as the win. But the case wasn't over. The government appealed. Ripple appealed back. And the judge had also ruled that Ripple's direct sales to big investors did break the law.
So the company that wanted to be inside the system still had to pay a bill. On August 7th, 2025, both sides dropped their appeals. The penalty stayed $125,35,150. The SEC's own release says the judgment stays in effect. That's the end of the lawsuit.
4 years, 7 months, and 16 days. But look at what Ripple did 5 weeks before that while the case was still open. On July 2nd, 2025, Garlinghouse announced Ripple was applying to the OC, the agency that charters national banks for a bank charter. Its subsidiary had also asked the Federal Reserve for an account.
Founded Standard Custody, which um is qualified custodian in New York. Ripple ultimately acquired Standard Custody about a year ago to become the issuer of RLUSD. That subsidiary is Standard Custody. It's a New York trust company. It's the company that issues RLUSD, Ripple's dollar coin, and it already answers to New York's banking regulator.
So, the plan was never be a crypto company the banks tolerate. The plan was be regulated twice, once by New York, once by Washington. Which regulator actually stands behind the things that you hold and whether it's the state, the feds, or nobody is the first thing that we check with our clients inside of the SGS system at Altcoin Pro. And in the link below, you can book yourself a free call to check that out. And in July of 2025, the Genius Act became law.
For the first time, Congress wrote down the rules for a dollar coin or stable coin. Ripple's application was already in. On December 12th, 2025, the OC said yes conditionally. Garlinghouse called it a massive step forward. Here's how it landed on your feed the next morning.
Ripple just got conditional approval from the OC to charter a national trust bank in the United States. This is not the average partnership headline in the crypto space. This is Ripple walking straight into the federal banking system through the front door. Through the front door, Ripple is a bank. Headlines ran with Ripple is now a bank.
That's not what conditional approval means. A conditional approval from the OC is permission to proceed toward becoming a bank, not confirmation that the bank is actually open and operating yet. But it wasn't not yet. A conditional approval is a permission slip to go build the bank. The OC's own letter spell this out.
Here's the sentence from an OC charter letter dated September 18th, 2026. Same kind of charter, different applicant. Final approval and authorization pursuant to 12 USC27A for the bank to commerce business will not be granted until a pre-opening requirements are met. So between December and October, Ripple had to build the thing. The money set aside, the people, the controls, and let the OC inspect all of it.
One explainer channel put the window at 18 months or about June 2027. You're probably thinking, I've been told the big moment is here for 6 years. December was the big moment, then it wasn't. And that's fair. So, here's the one thing that I check before I believe any Ripple is a bank headline.
Which word is in the letter conditional or final? That's the whole test. And in Garlinghouse's own words in February 2026, here's why Ripple wanted the second regulator at all. We do have a conditional OCC charter which is uh really for almost belt and suspenders regulatory oversight for our stable coin business. But we went kind of the extra step of having regulatory oversight both to the New York Department of Financial Services uh as a trust license.
Then we also went and uh applied for an OC charter which we now have conditional approval on. We think that uniquely positions us as you know almost overregulated. Uh, but we want that
belts and suspenders almost overregulated on purpose. Then on October 26th, 2026 at 4:22 in the afternoon, the day before swell, Garlinghouse posted the OC had granted final approval for Ripple National Trust Bank. Final. The word changed, but the word is not the job. So, keep reading.
Now, read what the bank is approved to do. This is Ripple's own release the same day. R&TB's approved activities include managing the segregated reserve supporting Ripple's RLUSD, acting as collateral trustee or the reserves for the benefit of RLUSD holders and providing fiduciary digital asset custody services, RNTB, Ripple National Trust Bank. So there's three jobs in plain words. One, hold the cash and treasury bills that sit behind RLUSD in a separate pile.
Two, be the trustee of that pile, which means the pile belongs to the people holding RLUSD, not to Ripple if Ripple ever goes under. Three, see where it says custody? That just means holding coins for somebody else. Hold crypto for businesses under the rules that govern a bank trust department. That's it.
That's a vault with a federal inspector. But look at what's missing. Here's what a national trust bank can't do. It can't take your deposit. It can't make a loan.
Reporting on the approval says exactly that. No deposits, no loans. The OC's charter letters say a trust bank will limit its operation to those of a trust company. This kind of bank is not small. By the way, the OCC's own letter says that as of March 31st, 2026, the trust banks it supervises held 7.2 2 trillion for other people.
Vaults, not lenders. So, Ripple got a new vault. Now, what did your coin get? Count the names in that approved activity sentence. RLUSD twice, holding coins for others once, XRP zero.
Count them in Garlinghouse's post. RLUSD once, holding coins once, XRP zero. That's not a trick, it's what the bank is for. On October 26, 2026, there was about $2.58 billion of RLUSD out there. The bank's first job is to guard the cash behind that $2.58 billion.
On the same day, there were about 63.35 billion XRP at about $130 each. The bank's letter doesn't say a word about any of them. You're probably thinking, "But a Ripple bank holding crypto for businesses has to be good for XRP." Maybe. But here's the honest version. The coin holding job is for companies, not for you and me.
Whether the first thing a big customer asks that vault to hold is XRP or Bitcoin or a treasury fund turned into a coin is the customer's call. Nothing in that letter puts XRP in the vault. What the letter does do is answer the 2020 question for the company. In 2020, the government said Ripple was running an illegal security sale. In 2026, the government's bank regulator says Ripple is fit to guard other people's money under federal inspection.
And the coins half of that question got answered separately. On March 17th, 2026, the SEC and the CFTC put out an interpretation that lists XRP as one of 16 digital commodities. That's the paper that moved your coin from security to commodity, not this one. Now, this is all very exciting for Ripple the company and RLUSD and hopefully XRP by relation, but unfortunately there's nothing in there to help regulate XRP to the upside. But that is why we are also waiting for the next move of the Clarity Act.
So, pay attention and subscribe if you're not because we do cover that as well. And one more thing about where your coins sit. If they're on an exchange, that exchange's own filings describe you as a creditor if it fails. A federally supervised trust bank holding coins as a trustee is a different legal animal. That's the real long-term story in this letter.
And it's a story about who holds your coins, not about price. Ripple wasn't alone in that December batch. On December 12th, 2025, the OC conditionally approved Circle, Paxos, and BitGo on the same day. The crypto companies are all walking in the same door, and the old banks don't love it. US controller Jonathan Gould.
Today's final rule advances to the president of United States and Secretary Scott Besson's vision for American leadership in digital assets. We are providing a clear practical framework for payment stable coin innovation with strong standards for reserve banking redemption and risk management. That's the comp troller Jonathan Gould 4 days before Ripple's letter laying out the stable coin rules that banks had been fighting. Garlingous's December release called the other side anti-inovation bank lobbyists. Now the clock swell Ripple's own conference runs October 27 through the 29th of 2026 in New York and Garlinghouse timed that post for the night before.
We're actually saying well we want to be the bridge between traditional finance and the decentralized finance world. So we're going to we're the decentralized finance piece. We're going to acquire things that are traditional finance.
The bridge between the old banks and crypto. That's the pitch that he'll make on stage. Here's what I would listen for. One, an opening date for the bank because final approval is still not open for business. Two, whether the word XRP ever shows up in the coin holding business from a customer's mouth, not Ripples.
Now, listen to him again. December 22nd, 2020, the day they sued.
XRP is a separate thing altogether. It is a currency that trades in the marketplace.
XRP is a separate thing altogether. Six years later, the government agreed with him on both halves. Ripple is a bank, a real one with a federal inspector that can hold cash and hold coins and can't lend a dollar. And XRP is a separate thing altogether, a commodity on paper since March 17th, 2026 that trades in the same marketplace, which is exactly where it was. What the letter doesn't settle when the bank opens and whether anyone ever asked it to hold XRP.
Ripple got into the building. Your coin is still outside and nothing in this letter walks it in. So tell me in the comments section December 22nd, 2020, one word, holding, buying, or out. Everything in this video came out of three documents. A 71page lawsuit from 2020, a one-page bank letter from 2026, and the release that explains it.
Nobody read them to you in a thumbnail. Reading the page the headline is built on, and then checking where your own coins actually sit is the job. And it's what SGS system inside of Altcoin Pro does with people line by line on what they already own. If you're holding $50,000 or more and nobody has ever sat down with you and mapped out who's actually holding it, that's who it's for. If you're not there yet, keep watching these videos.
These are free and I'm not going to stop making them. If this is money that you and your spouse decide on together, bring them onto the call as well. Bring a pen and paper. You're going to get a ton of notes to take as well. the first link in the description. Just click the more button and it'll show you the link right there at the top.
Book the call immediately. Crypto carries risk and past performance doesn't guarantee future results. This video is education, not financial advice. You know what to do. Stay bullish.
I'll see you at the top.
Education and commentary only, not financial advice. Crypto is volatile and you can lose money. Do your own research and speak to a qualified advisor before making investment decisions. Figures and quotes are as reported in the video on October 27, 2026 and may have changed since.


